
Reading Time: 10–12 Minutes
Executive Summary
Thousands of Pakistani freelancers and digital businesses receive international payments through Payoneer, Wise, Deel, Stripe, and similar platforms. However, the tax outcome depends not only on the payment platform but also on how the receiving bank classifies the incoming foreign exchange. Incorrect routing or coding may affect eligibility for the tax treatment available to qualifying export proceeds and can increase compliance risks.
Why This Issue Matters
Pakistan’s freelance economy has grown rapidly. Yet many professionals focus only on receiving money quickly and overlook the banking documentation that determines the regulatory classification of their foreign receipts.
The platform used to receive payment is only one part of the transaction. The receiving bank’s reporting and documentation play a critical role in tax compliance.
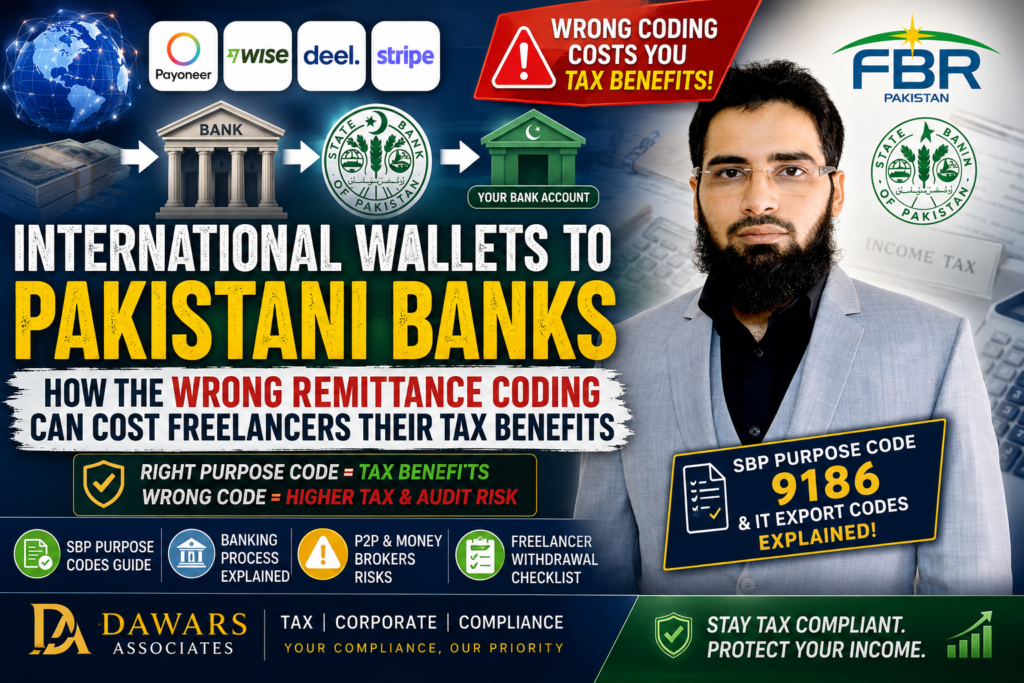
How Money Travels from an International Wallet to Your Pakistani Bank
Step 1 – International Client Makes Payment
The client pays through an international payment platform such as:
- Payoneer
- Wise
- Deel
- Stripe
Step 2 – Payment Network
The wallet processes the payment through its banking partners and international payment infrastructure.
Step 3 – Foreign Exchange Realization
Funds enter Pakistan through the authorized banking system, where they are reported under the State Bank of Pakistan’s foreign exchange reporting framework.
Step 4 – Purpose Code Assignment
The receiving bank assigns the applicable SBP purpose code based on the nature of the underlying transaction. Freelancers should confirm that the code accurately reflects the exported service. Where a bank uses Purpose Code 9186 for an eligible category of digital service exports, it should be correctly applied.
Step 5 – Credit into Local Bank Account
Only after these steps is the amount credited to the customer’s account.
Why Purpose Codes Matter
Purpose codes are not merely administrative labels. They identify the nature of the foreign exchange transaction for regulatory reporting.
Correct classification helps establish that the funds relate to eligible export services, supporting the appropriate tax treatment where legal requirements are met.
The Hidden Risk of Generic Remittance Coding
Some payments may be processed using a generic inward remittance description instead of an export-related purpose code.
Potential consequences include:
- Additional compliance questions
- Greater documentation requirements
- Difficulty establishing export realization
- Possible disputes regarding the applicable tax regime
Why P2P Transfers and Money Brokers Create Problems
When freelancers exchange foreign balances through private buyers or informal channels, they may lose the banking trail that supports export realization.
Possible issues include:
- Missing official banking evidence
- Weak audit trail
- Higher compliance risk
- Difficulty substantiating the source and nature of funds
Using authorized banking channels is generally the safer approach.
Comparison Table
| Factor | Compliant Export Remittance (Applicable IT Purpose Code) | Generic/P2P Transfer |
| Banking Documentation | Strong | Often Limited |
| Export Evidence | Available | Weak or Missing |
| Regulatory Trail | Complete | Incomplete |
| Eligibility for Export Tax Treatment | Subject to legal requirements | May be difficult to establish |
| Audit Risk | Lower when properly documented | Higher |
Freelancer Bank Withdrawal Checklist
Before withdrawing funds:
- Confirm the payment is being processed as export proceeds where applicable.
- Ask which SBP purpose code has been assigned.
- Request a bank advice or transaction confirmation.
- Retain invoices and client contracts.
- Keep platform statements from Payoneer, Wise, Deel, or Stripe.
- Preserve proof of foreign client payments.
- Reconcile wallet statements with bank credits.
- Consult a tax adviser if there is any uncertainty about the transaction’s classification.
Practical Example
A digital marketer receives USD 2,500 from an overseas client.
If the payment is processed through authorized banking channels with the correct export classification and supporting records, the taxpayer is generally in a stronger position to support the applicable tax treatment.
If the same amount is received through informal exchange arrangements or without proper banking documentation, additional compliance issues may arise.
Frequently Asked Questions
Does receiving money through Payoneer automatically qualify for export tax treatment?
No. The platform alone does not determine tax treatment. The nature of the underlying service, banking documentation, applicable SBP reporting, and the Income Tax Ordinance all matter.
Can I sell my Payoneer balance to another person?
Informal exchanges may weaken your documentary trail and create avoidable compliance risks.
Should I keep invoices?
Yes. Invoices, contracts, platform statements, and bank advice together provide a stronger audit trail.
Should I ask my bank about the purpose code?
Yes. Confirm that the code accurately reflects the exported service and request supporting documentation where available.
Final Thoughts
Receiving international payments correctly is not only about convenience—it is also about protecting your tax position and maintaining a clear documentary trail.
By using authorized banking channels, verifying the applicable SBP purpose code, and retaining complete supporting records, freelancers and digital businesses can significantly strengthen their compliance with Pakistan’s foreign exchange and tax requirements.
Need Professional Assistance?
Dawars Associates
Specialists in:
- Pakistan Income Tax
- Freelancer Tax Advisory
- IT Export Taxation
- International Tax Compliance
- Foreign Remittance Documentation
- Corporate Tax Planning
- US LLC Compliance
- Accounting & Bookkeeping Services
Disclaimer: This article is for general educational purposes and should not be treated as legal or tax advice. Tax treatment depends on the specific facts of each case, applicable law, and current SBP and FBR requirements.
Written By: Khalid Iqbal
Tax & Corporate Consultant
Dawars Associates
Tax | Corporate | SECP | FBR Consultancy
Rawalpindi / Islamabad, Pakistan
📧 CEO@dawarsassociates.com
📞 0333-5191977
🌐 www.dawarsassociates.com
📍 Also follow us on LinkedIn, Facebook & YouTube for weekly tax insights.

